Florida Physician Home Loans

Florida Physicians Often Need More Than a Conventional Preapproval

Whether you're relocating to Miami, Tampa, or Orlando, your mortgage strategy matters as much as your income.

Florida's healthcare employment is growing fast—and physicians moving from out of state often arrive with a new contract, no Florida income history, and student loan debt that traditional underwriting handles poorly. A preapproval that doesn't account for those variables can create serious problems when it counts. NEO helps Florida physicians build a financing strategy before they start shopping.
Get Your Florida Physician Mortgage Strategy See why physicians get declined
Strategy before preapproval Physician-focused underwriting Quick answers, no runaround
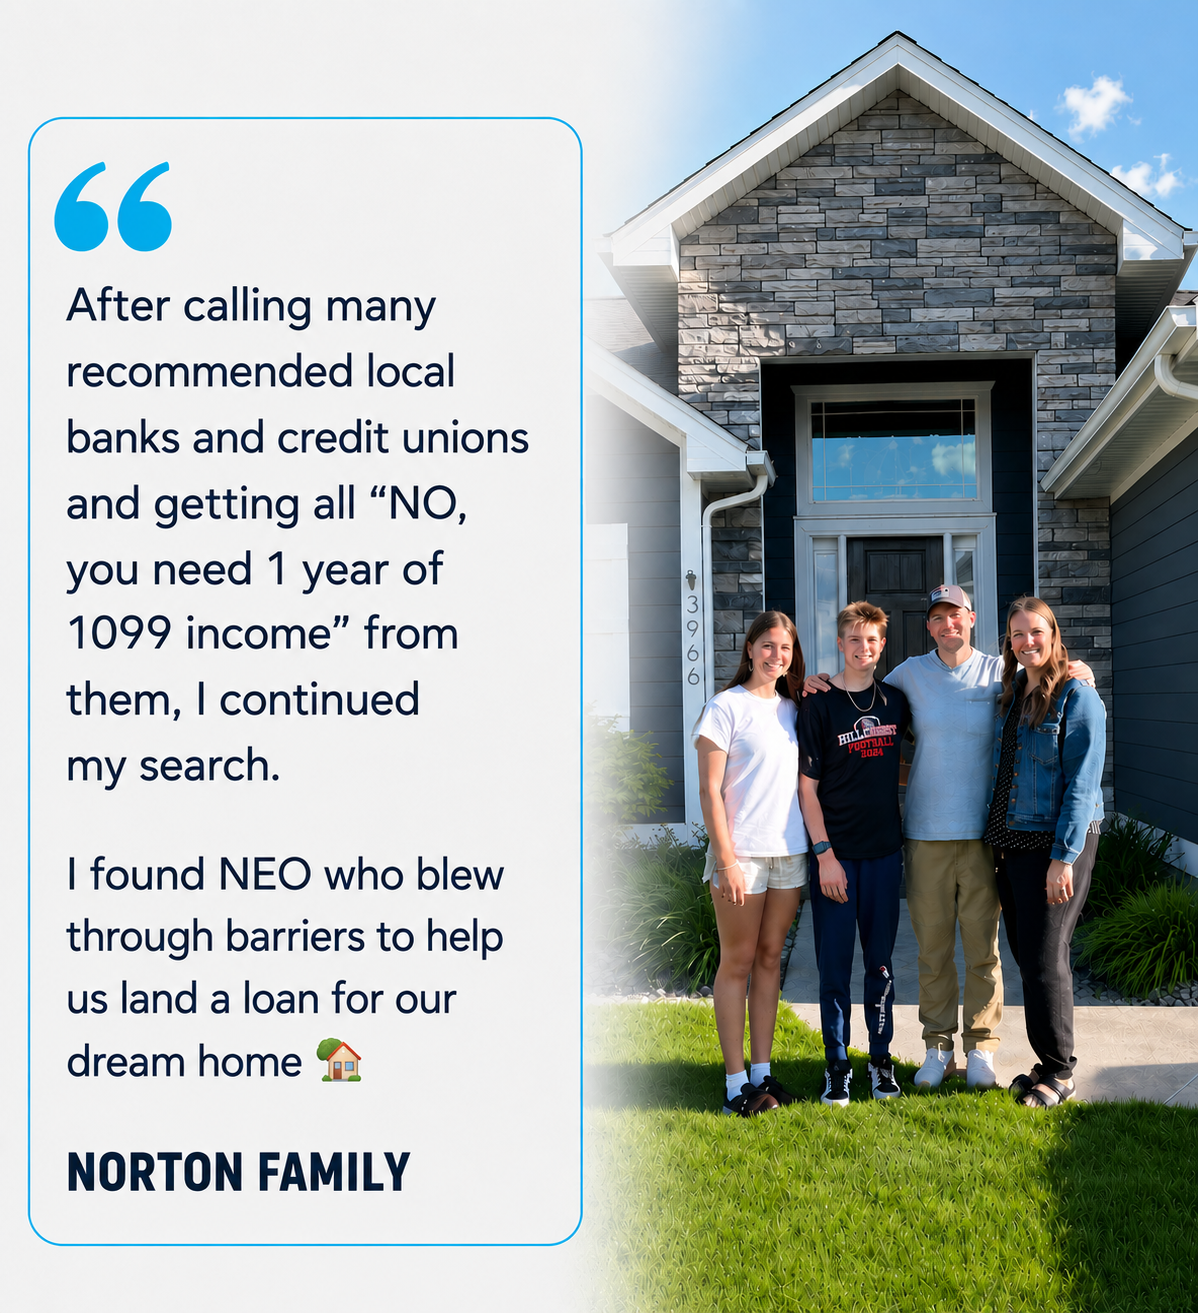
Other banks said no. Complex income approved. — The Norton Family in front of their new home
Physician exclusive
100%
financing
no down payment

Now offering up to $3,000,000 in financing — including zero down on loans up to $2M, with no mortgage insurance.

See if you qualify

The paradox

The problem isn't that physicians are weak borrowers. It's that physicians are complex on paper.

Student loans
Residency transitions
Fellowship programs
Future income
Employment contracts
Practice ownership
1099 compensation
Jumbo financing

These factors create mortgage land mines that many lenders don't identify until after you've started house hunting, submitted an offer, or committed earnest money. Our process begins with a strategy-first review designed to uncover concerns and create a clear path forward.

Why physicians get declined

Why Florida physicians get declined for home loans.

You have strong earning potential and professional stability. But underwriting evaluates how your income, assets, liabilities, and documentation fit the guidelines — and that's where physicians run into trouble.

01

Student Loan Calculations

IDR plans, deferred loans, and large balances are calculated differently by program. The wrong calculation can significantly reduce purchasing power.

02

Employment Contract Issues

A signed contract doesn’t automatically qualify as income. Contract language, start dates, and contingencies all matter.

03

Residency & Fellowship Transitions

Moving between programs, hospitals, or cities creates qualification challenges traditional lenders rarely encounter.

04

Future Income Challenges

Many physicians buy a home before the first paycheck. The income is real — the challenge is documenting it correctly.

05

Jumbo Loan Requirements

Many physician purchases fall into jumbo financing, where underwriting standards become more restrictive.

06

Weak Preapprovals

Automated or lightly reviewed approvals often fail to identify underwriting concerns until much later in the process.
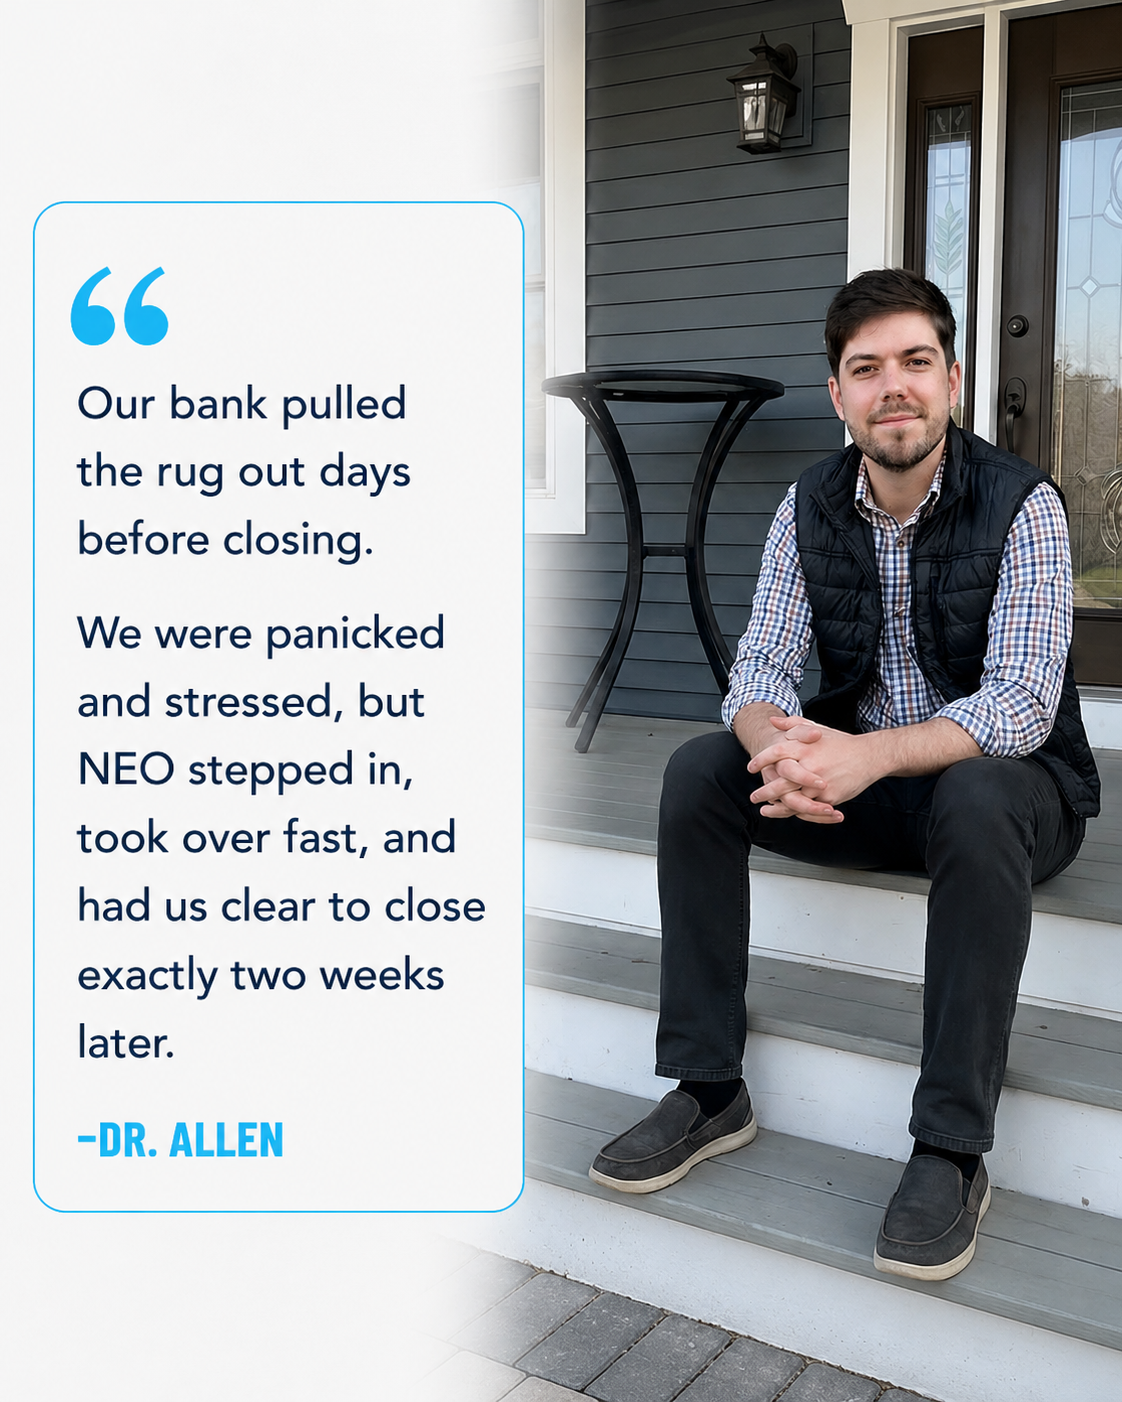
Testimonial: Our bank pulled the rug out days before closing. NEO stepped in and had us clear to close two weeks later. — Dr. Allen

Our review process

Most mortgage problems start long before underwriting.

They start when potential issues go undiscovered. That's why our process begins with a physician-focused strategy review.

1

Review Your Financial Profile

We evaluate income, student loans, assets, employment contracts, credit, and documentation.

2

Identify Potential Underwriting Risks

We look for issues that could create challenges later in the process.

3

Evaluate Available Loan Options

Different programs treat physician income, student loans, and contracts differently.

4

Build a Mortgage Strategy

You get a clearer understanding of your options and next steps before making major housing decisions.

The goal is simple: help you move forward with confidence before you make an offer, relocate, or commit to a purchase.

Who we help

Florida physician home loan programs for every career stage.
PhysiciansResident PhysiciansFellowsDentistsVeterinariansCRNAsPhysician AssistantsNurse PractitionersPharmacistsPractice OwnersIndependent Contractors1099 PhysiciansHigh-Income Professionals

Resident Physician Home Loans

Many residents assume student loan debt automatically prevents homeownership. That is not always true. Depending on your situation, contract status, loan program, and student loan structure, there may be options available. We help residents understand qualification strategies before they begin house hunting.

Evaluate my options →
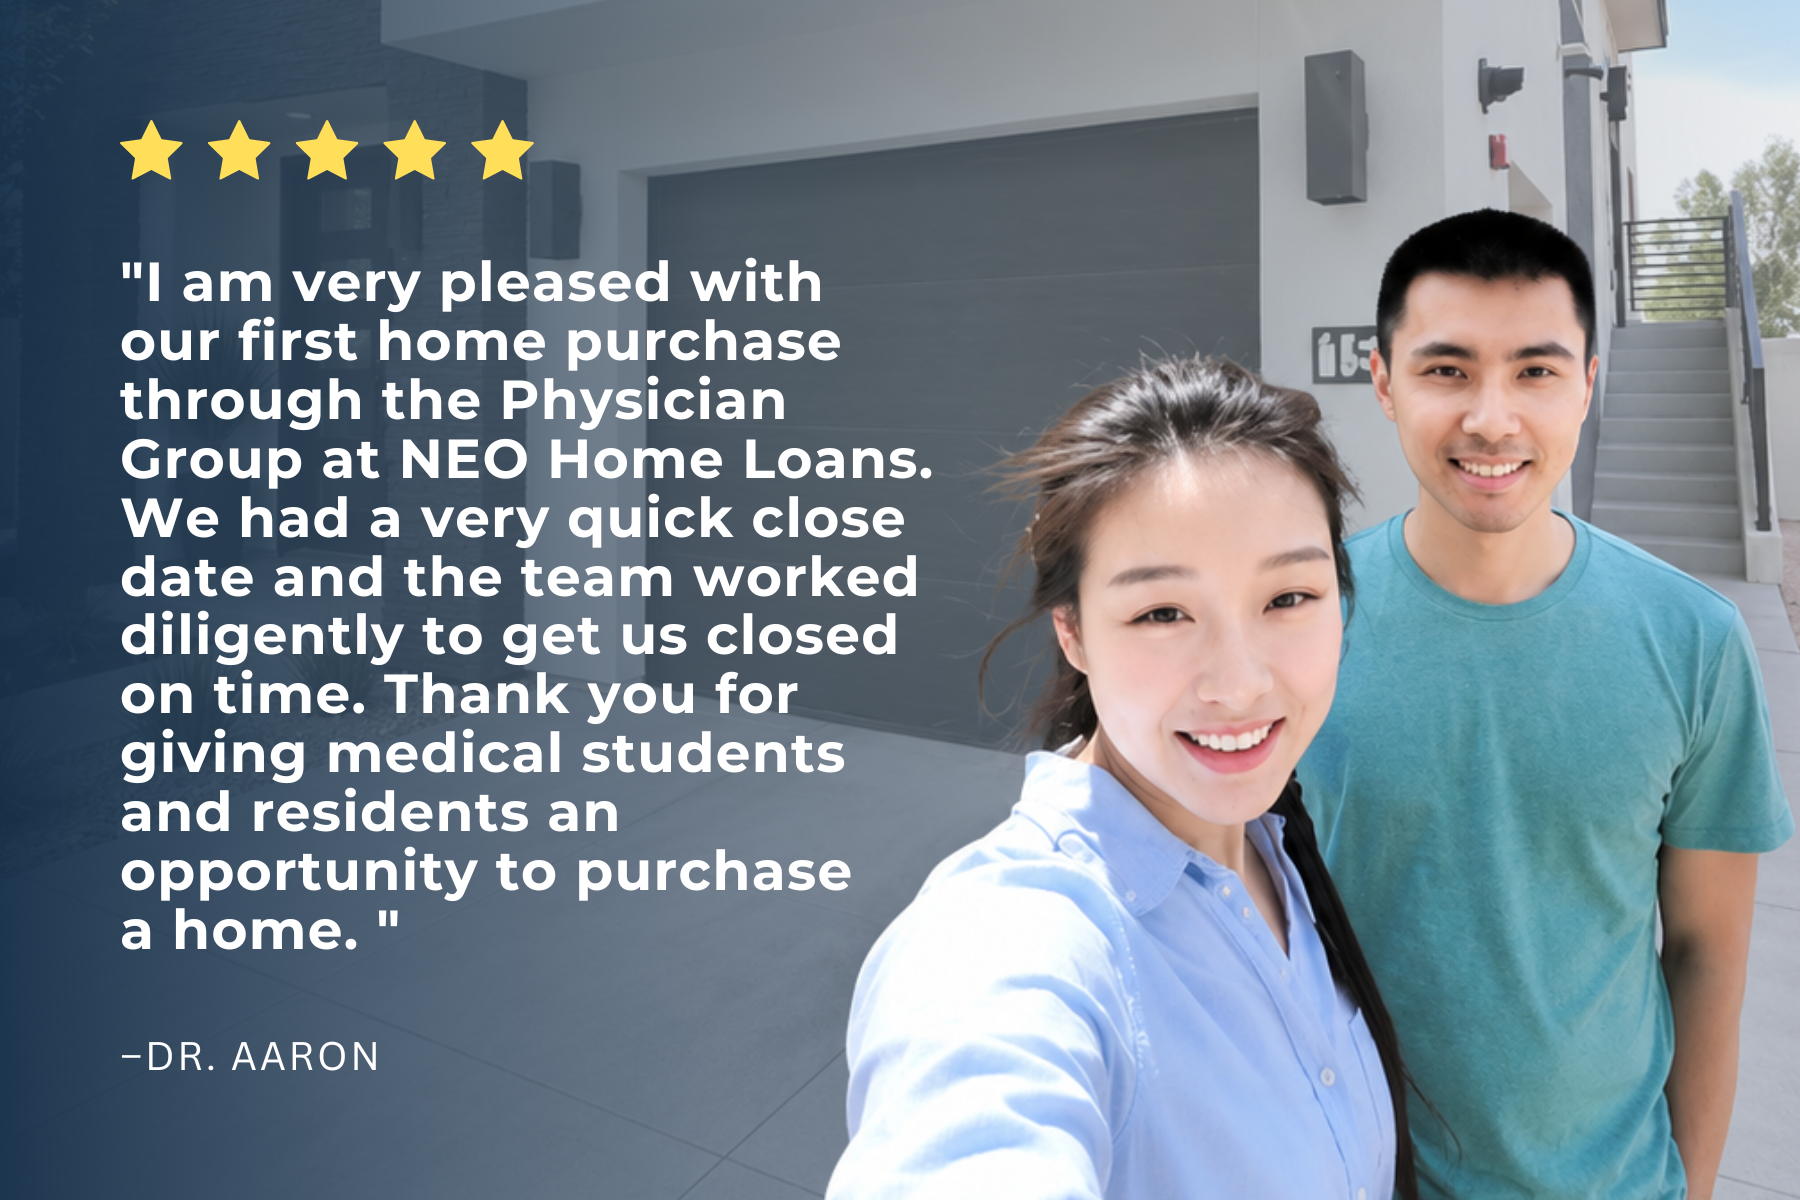
Five-star review from Dr. Aaron: very pleased with our first home purchase through the Physician Group at NEO Home Loans.

Program details

What the physician loan program offers.

Financing tiers

100% financing
up to $2,000,000
90% financing
up to $3,000,000

Loan amounts above reflect program maximums by financing level.

Program highlights

No private mortgage insurance
Gift funds acceptable
Close prior to employment start date
Flexible with student loan debt
1099 income with a guaranteed salary accepted
Hourly rate with stated hours accepted

Student loans

The most misunderstood part of physician qualification.

The way student loans are calculated can significantly impact purchasing power. Understanding the answers before applying helps prevent surprises later.

Q How do student loans affect mortgage approval?
+
Student loans factor into your debt-to-income ratio — the monthly payment used in that calculation depends on your repayment plan and the loan program you apply under. Some physician mortgage programs use your actual IBR or IDR payment. Others apply 0.5–1% of your total balance monthly regardless of what you currently pay. The difference can meaningfully change how much home you qualify for.
Q Can deferred student loans impact qualification?
+
Yes. Even loans in deferment count under most programs — lenders apply a percentage of the total balance as an assumed monthly payment rather than using $0. Physician-specific loan programs often treat deferred loans more favorably than conventional guidelines do, but the rules vary. Knowing exactly how your deferred balance is treated before you apply prevents surprises at underwriting.
Q How are IDR and IBR payments calculated for mortgage approval?
+
Income-Driven Repayment and Income-Based Repayment payments are set as a percentage of your discretionary income, which can result in a very low or even $0 monthly payment. Many physician loan programs will use your actual documented IDR/IBR payment in the DTI calculation — which significantly improves qualifying power compared to programs that use a percentage of the balance. Correct documentation of the payment amount is what makes this work.
Q Can I qualify with significant medical school debt?
+
Yes — physicians with substantial loan balances qualify regularly. The key variable is which program you use and how it treats your balance. A $400K balance at 1% monthly adds $4,000 to DTI. That same balance under a program using your $200 IBR payment adds only $200. Selecting the right program for your specific loan situation is often the difference between qualifying comfortably and not qualifying at all.
Q Which loan programs treat physician student loans differently?
+
Physician-specific mortgage programs — distinct from conventional, FHA, or VA loans — are designed to accommodate high student loan balances. Depending on the program, they may accept your actual IBR/IDR payment, exclude deferred loans from DTI entirely, or apply a lower percentage of the balance than conventional guidelines require. The right program depends on your loan structure, repayment plan, and purchase parameters — which is why reviewing this before you select a program matters.

Relocating to Florida

Moving for residency, fellowship, or a new attending role?

Understanding your mortgage options before relocating creates a smoother transition. We regularly assist medical professionals across the state.

Areas we serve

MiamiJacksonvilleTampaOrlandoFort LauderdaleSt. PetersburgSarasotaNaplesBoca RatonWest Palm BeachGainesvilleTallahasseePensacolaCoral GablesAventura

Health systems we know

AdventHealth
Baptist Health South Florida
University of Florida Health
Tampa General Hospital
NCH Healthcare System

Relocating from New York, New Jersey, or another high-tax state?

Florida's no-income-tax advantage is real — but your income was earned and documented in a state with a different tax structure. When a lender reviews your income history and sees New York or New Jersey W-2s, the income-to-take-home comparison can confuse underwriters who aren't familiar with the transition. We prepare that file correctly from the start.

Joining UF Health, Baptist Health, or AdventHealth?

Florida's health systems hire nationally, which means many physician buyers arrive with a Florida employment contract and income history from another state. The contract qualification path has clear guidelines — but only if the loan is structured around those guidelines from the beginning.

Buying in Sarasota, Naples, Boca Raton, or South Florida?

Florida's coastal markets are some of the most expensive in the state, with Sarasota and Naples in particular having appreciated sharply over the past several years. Home prices in these markets frequently push into jumbo territory, and the resort-market characteristics of some properties can affect program eligibility.

Florida physicians with 1099 or independent practice income?

Florida has a large and growing independent physician community — particularly in specialties like psychiatry, hospitalist medicine, and private surgical groups. Income earned through a medical LLC, partnership, or 1099 arrangement has a workable path to approval, but the documentation needs to be built in advance, not assembled at the last minute.

The basics

What is a Florida physician home loan?

Florida's physician mortgage market is shaped by two realities that don't always cooperate: a massive physician relocation wave that brings buyers with complex out-of-state income documentation, and coastal housing markets that have appreciated significantly enough to push even routine purchases into jumbo territory. A physician moving from New Jersey to Boca Raton isn't making a financially simple move even if the sticker price looks lower than what they left behind — because the income documentation, property insurance implications, and loan program landscape are all different in Florida.

The no-income-tax advantage is the single most cited reason physicians give for relocating to Florida. What they don't always anticipate is that the take-home advantage they're expecting doesn't show up in their mortgage file right away — their income history reflects earnings in a state where taxes reduced their net pay, and the comparison can create underwriting questions. Beyond documentation, Florida's HOA-heavy residential landscape, flood insurance requirements in many coastal areas, and the dramatic price appreciation in markets like Sarasota and Naples mean that physician buyers need to build their mortgage strategy around Florida-specific realities, not a generic template.

Why physicians choose us

Why Florida physicians choose NEO.

Strategy Before Preapproval

Many lenders issue preapprovals before reviewing the details that matter. We believe clarity should come before commitment.

Physician-Focused Expertise

Medical professionals face mortgage scenarios that traditional lenders rarely encounter.

Proactive Underwriting Review

We work to identify potential concerns before they become closing delays or loan denials.

Student Loan Strategy

Student loans are one of the most common reasons physicians encounter qualification challenges.

Contract-Based Guidance

Employment contracts, future income, and start dates often require specialized review.

Relocation Experience

We help coordinate contracts, start dates, housing timelines, and financing considerations.

Get started

See what you qualify for.

Tell us a little about your situation and a Florida physician loan specialist will review your options with you — strategy first, before you make an offer.

By submitting this form, you agree to our privacy policy and consent to receive communications.

FAQ

Frequently asked questions

Does moving to Florida for the no-income-tax advantage affect my mortgage? +
Yes — in a way most physicians don't anticipate. Your income history reflects earnings in a state where taxes reduced take-home. When you arrive in Florida with your new contract, the income documentation picture has changed, but your mortgage file still reflects the old state. That transition requires specific handling to avoid underwriting confusion.
Are flood insurance requirements in Florida a factor in physician mortgage approval? +
In many coastal and low-lying Florida markets, flood insurance is required — and it adds to your total monthly housing cost, which affects DTI calculations. Properties in FEMA flood zones require National Flood Insurance Program coverage or private alternatives, and the cost can vary significantly by location. This is a factor we account for in your total payment picture before you shop.
Can Florida physicians buy using an employment contract from UF Health or AdventHealth? +
In most cases, yes. Physician loan programs accommodate contract-based income qualification. What matters is start date, contract structure, income verification, and which program your loan falls under. We review this before you begin searching so there are no surprises when you find the right property.
Why have Sarasota and Naples become harder markets for physician buyers? +
Both markets experienced significant post-2020 appreciation driven by retiree and relocation buyer demand. Home prices that were in conforming territory a few years ago now routinely require jumbo financing, and the resort and seasonal-market characteristics of some properties affect which loan programs are available. Knowing this before you shop changes your strategy.
Are physician home loans available for residents at UF, USF, or University of Miami? +
Some physician loan programs are available for residents depending on loan amount, credit, down payment, and profession. Florida has a large residency pipeline across Gainesville, Tampa, and Miami — and the markets around those programs vary significantly in price and competitiveness.
Can Florida 1099 physicians and practice owners qualify for physician home loans? +
Yes. Florida has a large independent physician community, particularly in specialties that operate outside hospital employment. Self-employment income through a medical LLC or partnership has a clear qualification path, but the documentation — two years of tax returns, business financials, and income verification — needs to be reviewed and prepared in advance.
How do HOA rules affect physician home loans in Florida communities? +
Many Florida communities are governed by HOAs with financial and structural characteristics that affect whether a property qualifies for certain loan programs. A community with high owner-occupancy, low delinquency rates, and adequate reserves is straightforward. Newer communities or those with management issues can limit which programs are available for a specific purchase.
What are the most common reasons Florida physicians run into mortgage problems? +
The most common issues: income documentation that reflects out-of-state earnings in a structure that doesn't translate cleanly to Florida, flood and HOA insurance costs that weren't factored into DTI, jumbo loan requirements in coastal markets where prices have risen, and employment contract qualification that wasn't reviewed before the offer was made.
Is Coral Gables or Aventura a different lending environment than Jacksonville or Orlando? +
Meaningfully so. South Florida's coastal markets — Coral Gables, Aventura, Boca Raton — operate in a luxury and international buyer context where property values, HOA structures, and market dynamics differ from inland Florida markets like Orlando or Tallahassee. The loan program and strategy that works in Jacksonville isn't always the right one for a Boca purchase.

Get clarity first

You are not a weak borrower. You're a complex one.

The right strategy helps you identify potential mortgage land mines and move forward with confidence — before you make an offer, before you relocate, before underwriting discovers a problem.

Schedule Your Strategy Call Talk With a Loan Specialist

Serving physicians and medical professionals throughout Florida.